How SC law splits the cost — the default rule
Pickens County puts a large share of its housing stock on forested slopes. Along the ridge roads outside Easley and in the coves west of Clemson, it is common for a neighbor's uphill hardwood to overtop a roof by thirty feet or more. When one comes down, the first question every homeowner asks is who writes the check — and SC's answer will surprise most people.
South Carolina follows a negligence-based standard for tree disputes, not a strict-liability one. A structurally sound tree that falls during a storm is treated legally as an act of nature. Each property owner bears responsibility for damage to their own land and structures. Your homeowner's insurance covers your loss; your neighbor's policy does not automatically owe you anything. The negligence exception — when that changes — is covered in the next section. The table below maps the common scenarios:
| Scenario | Who typically covers the damage |
|---|---|
| Healthy tree falls in a storm | Your homeowner's insurance — Coverage A for the dwelling |
| Dead or diseased tree, no prior notice given | Likely your insurance; negligence possible but harder to prove without documentation |
| Dead or diseased tree — neighbor had written notice | Neighbor's liability insurance (the notice establishes negligence) |
| Overhanging branches, tree still standing | Your right to trim to the property line, at your own cost |
| Tree falls on your vehicle | Auto comprehensive coverage, not homeowner's |
| Shared fence or outbuilding damaged | Coverage B (other structures); negligence may draw both insurers in |
Clemson Cooperative Extension's Home and Garden Information Center publishes guidance on identifying structural defects in landscape trees — the same criteria an arborist uses when writing the report that supports a negligence claim.
When the neighbor's insurance actually owes you
The negligence exception is real, but it has a specific shape in SC. To shift liability to your neighbor you generally need to show three things: the tree was visibly hazardous — dead wood, significant lean toward your property, fungal conks at the base, or major prior storm damage that was never properly addressed; the neighbor had actual notice of that condition; and they failed to take reasonable action. Notice is the pivot point. A storm record is not notice. You must have communicated the problem in a way you can prove.
Pickens County's position in the Blue Ridge foothills sharpens this dynamic. The county has recorded 23 federal disaster declarations over 2005-2026. Repeated storm cycles leave trees with internal decay that isn't visible from the street. A tree that looked intact may have been structurally compromised for years. If your neighbor patched surface storm damage to a trunk rather than having it assessed by a licensed arborist, and that tree later falls on your house, that repair history is evidence of notice.
The SC Forestry Commission offers hazardous tree assessment resources and can help document canopy risk — useful before you send a formal notice letter. When you do send it, use certified mail with return receipt. Describe the tree's location, its visible condition, and your concern that it poses a threat to your property. Keep the green card and a dated copy. That document converts a future storm loss into a documented negligence case against your neighbor's liability coverage.
For licensed removal contractors, SC requires compliance with SC Contractor Licensing Board standards. If a neighbor hired an unlicensed crew that left a tree structurally compromised, that history is relevant to the negligence analysis.
What your homeowner's policy actually covers — and the sublimit trap
Even when your insurer is handling the loss, the policy has gaps most homeowners discover only after the fact. For the full picture, see what homeowner's insurance actually covers for tree removal. The items to know before you file a claim:
Structural damage to the dwelling (Coverage A) is covered regardless of whose tree caused it. The surprise is debris removal. Most policies include a sublimit for fallen tree debris — commonly $500 to $1,000 per occurrence, or a small percentage of the dwelling limit. When a 60-foot white oak slides off a Pickens County ridge and pins itself across a living room, removal alone can run $2,500 to $5,000 or more depending on access and how far the crown has engaged the structure. That gap between the sublimit and the actual invoice is out of pocket unless you establish the neighbor's negligence.
Fencing, sheds, and detached carports fall under Coverage B (other structures), typically capped at 10% of the dwelling coverage limit. A neighbor's tree that takes out a fence run and a storage building can exhaust that sublimit quickly. Vehicles are covered only under comprehensive auto coverage — not under a homeowner's policy at all.
One path to recovering your deductible: if your insurer pays the claim and later determines the neighbor was negligent, they may subrogate — pursue the neighbor's carrier on your behalf. That process takes time, but it can eventually eliminate your out-of-pocket cost. Keep all repair invoices and document every conversation with both insurers in writing.
The first 48 hours: what to do before anything gets moved
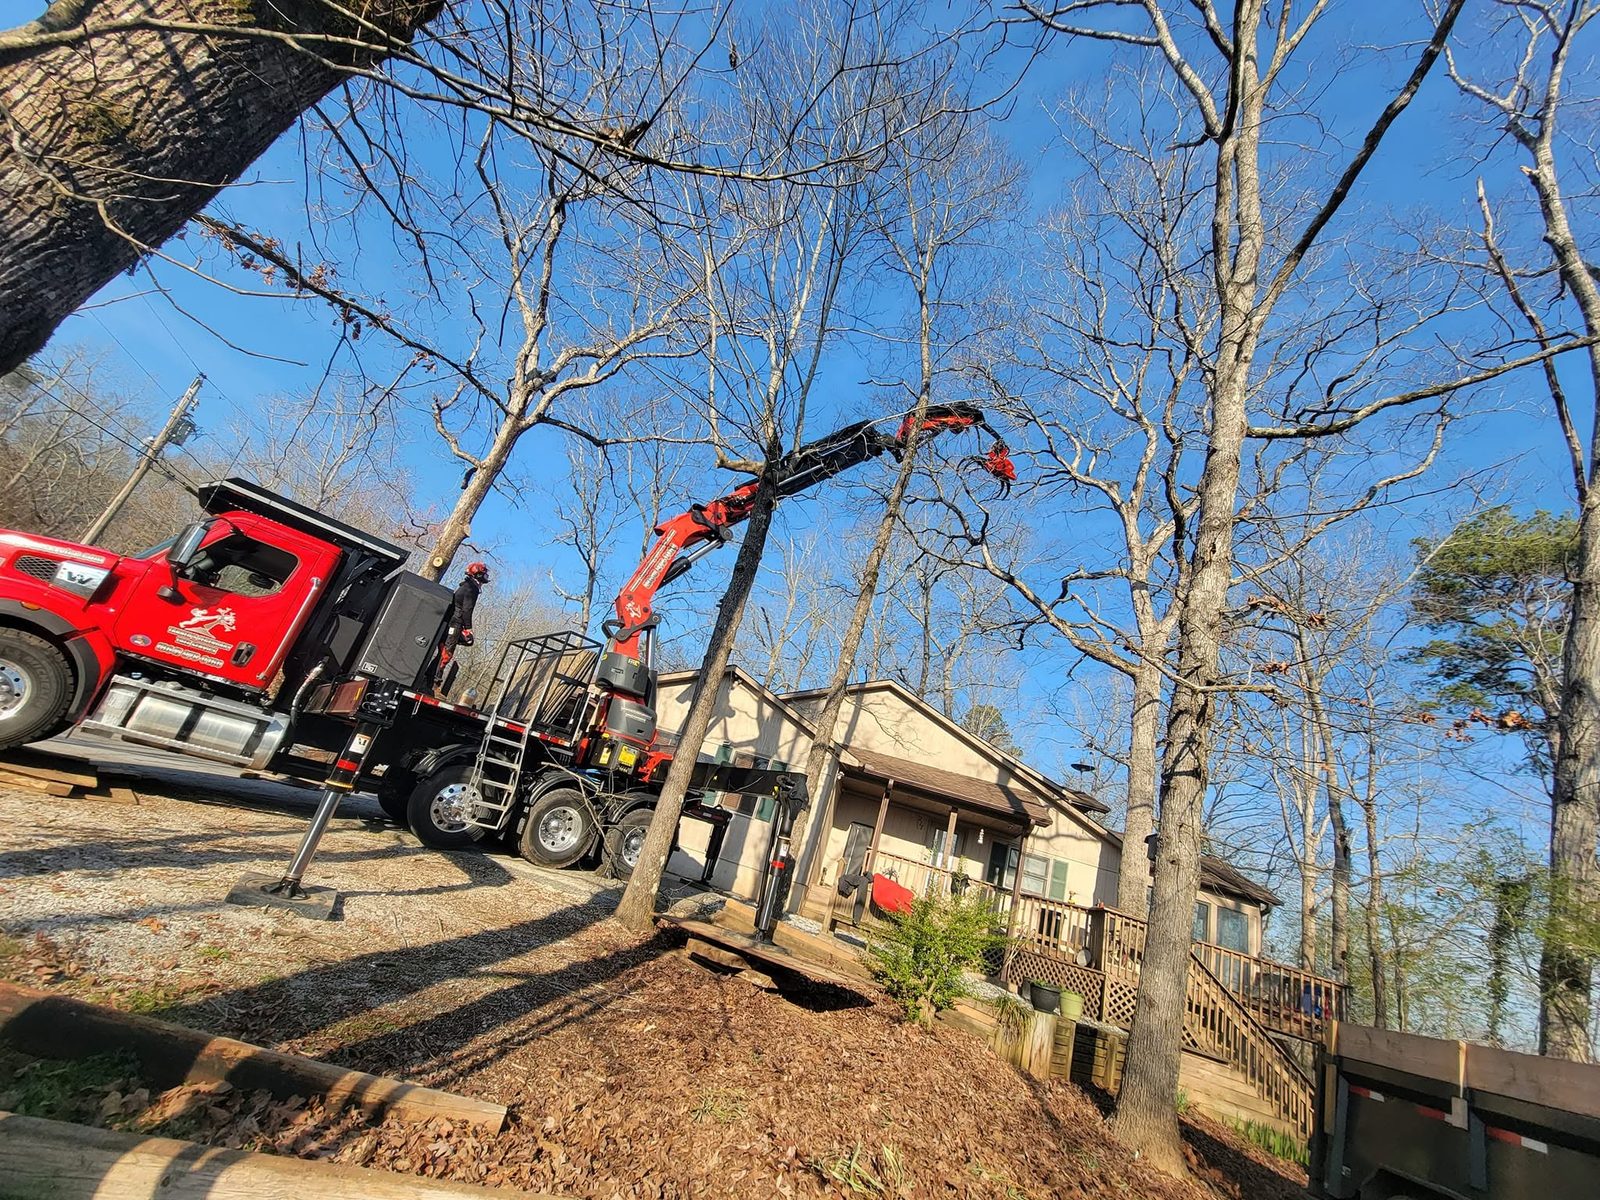
The decisions you make in the first two days largely determine how the claim resolves. On steep Pickens County lots, a half-fallen tree on a slope can shift with rain or a wind gust and cause secondary damage — or become a hazard for anyone working near it. Act in this order.
Document everything before cleanup begins. Photograph and video the full scene: the tree, the break point (root ball uplift, trunk failure, or crown separation), all damage to the structure, and the stump. If the root ball or stump shows internal decay, capture it closely before the site is disturbed. That evidence disappears once the tree is cut and hauled. This documentation also protects you against any later claim that the structural damage was pre-existing.
Open a claim with your insurer before authorizing significant cleanup. Adjusters want to see damage in place. Most policies require reasonable mitigation — tarp a leaking roof, board broken windows — but full debris removal should wait for adjuster sign-off unless safety requires it. For any situation where the tree is actively threatening the structure or occupants, contact emergency tree service immediately and document why it could not wait for the adjuster.
Preserve evidence of the neighbor's tree condition. Before the stump gets ground and the root ball gets cleared, photograph any visible rot or decay. If the break point shows obvious internal deterioration, that photograph is the foundation of a negligence case. After the immediate hazard is resolved, the storm cleanup process can move forward in a way that preserves your claim record.